
What Happens When a Car Is Repossessed: A Quick-Reference Guide
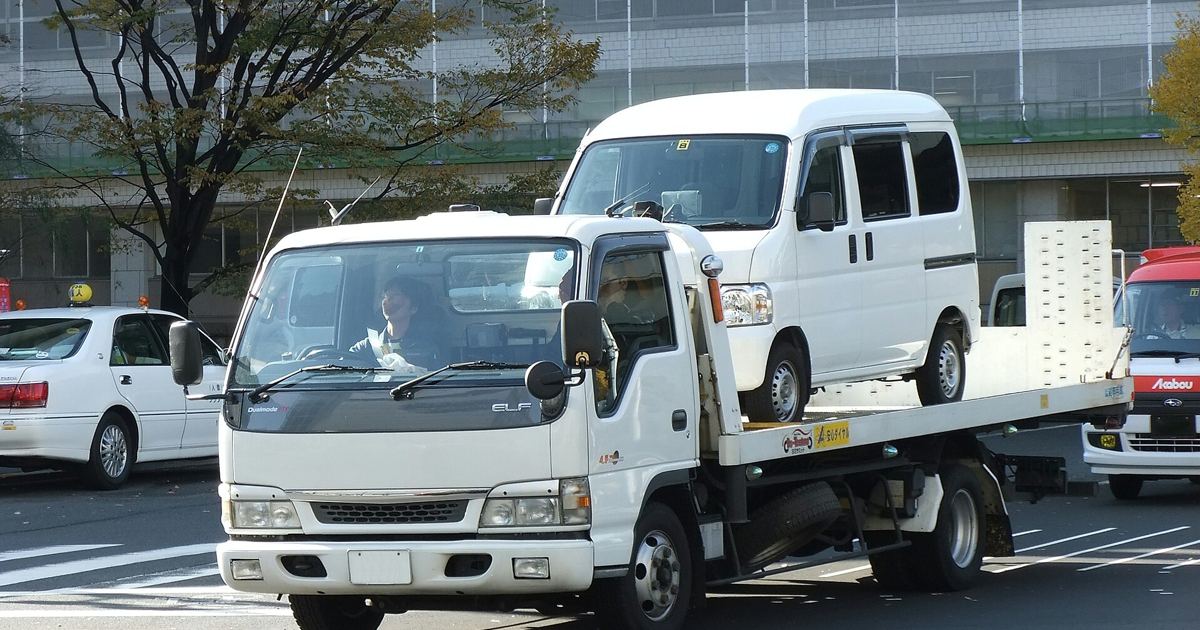
Losing a vehicle because you were unable to make your auto loan payments is a major financial disruption, but auto loan servicers are required to follow strict legal boundaries throughout the entire process. Whether you are facing a potential repossession or your vehicle was already taken, federal and state rules provide specific consumer protections. This quick-reference guide breaks down the rules governing pickup, your personal property, vehicle resale, and lingering debt balances.
Advance Notice Rules and Military Protections
Whether you receive prior warning depends heavily on your state of residence and your military status. Under standard state laws:
- No-notice states: In many states, a lender is permitted to repossess your vehicle without providing an advance warning or obtaining a court order as soon as you have missed a loan payment.
- Notice-required states: Other states legally mandate that lenders or servicers issue a written notice before taking the vehicle. This alert must identify which payments were missed and give you a specific timeframe to catch up.
Stronger protections apply to active-duty service members under federal law. As outlined by the Consumer Financial Protection Bureau (CFPB), the Servicemember Civil Relief Act (SCRA) strictly prohibits lenders from carrying out a repossession without a court order for any auto loan agreement entered into before beginning military service.
Limits on Lenders: Breaching the Peace
Even in jurisdictions where lenders do not need a court order to seize a vehicle, repossession agents are strictly forbidden from "breaching the peace" under state law. Actions that generally constitute an unlawful breach of the peace include:
- Threatening you or using physical force at any point during the repossession.
- Entering and removing a vehicle from an enclosed, closed garage without explicit permission.
- Proceeding with the repossession after you have verbally or physically resisted or refused to permit the seizure.
If an agent breaches the peace while taking your vehicle, you have the right to contact law enforcement right away. In addition to addressing immediate safety concerns, an unlawful breach of the peace can establish a legal defense or a valid claim for damages, which can potentially reduce the final balance you owe following the sale of the car.
Your Rights Regarding Personal Property Inside the Car
Losing access to your vehicle does not mean giving up ownership of the belongings left inside it. Repossession companies are not permitted to seize your personal items along with the car. You should immediately reach out to your lender to schedule an appointment to retrieve your personal property.
Before heading to the recovery yard, write down a detailed inventory documenting each item left in the cabin or trunk alongside an estimated dollar value for each piece. If the repossession contractor or lender insists that you pay an upfront fee before releasing your property, seek legal advice. In a formal enforcement action, the CFPB determined that withholding personal belongings until consumers paid an upfront fee is an unfair act or practice. If you encounter this issue, you can file an official complaint with your state attorney general or your local state consumer protection office.
Getting the Vehicle Back: Curing and Redemption
Depending on where you live, you may have legal avenues to recover your repossessed vehicle before it is permanently disposed of:
- Loan reinstatement (curing the loan): Certain state statutes give borrowers the right to make up past-due loan payments alongside repossession costs within a set window of time to get the vehicle back.
- Loan redemption: Across most jurisdictions, you retain the right to redeem the car before it is sold by paying the entire remaining loan balance in full, in addition to reasonable repossession fees.
Lenders must also provide formal notification before disposing of the vehicle. For a public auction, the lender must send advance notice stating the exact date, time, and physical location of the sale so you have the opportunity to attend and bid. For a private sale, the servicer must notify you of the specific date after which the car could be sold.
Deficiency Balances, Surpluses, and Fees
A repossession does not necessarily extinguish your remaining loan obligations. Once the vehicle is sold in a commercially reasonable manner, the proceeds are applied against your debt:
- Repossession fees: Your lender will typically add a fee for picking up the car. By law, this pickup fee must be reasonable based on the vehicle type, the location, and how the repossession was performed. You can request an itemized list of all repossession charges directly from your lender.
- Deficiency balance: If the vehicle sells for less than your total debt plus fees, you remain responsible for the unpaid difference. For instance, if your loan balance is $10,000 and the lender sells the car for $7,500, you are responsible for paying the $2,500 deficiency balance, plus all repossession fees. If you fail to resolve that balance, the lender can place the debt with a collection agency or hire a debt collector to pursue payment.
- Surplus balance: If your car sells for more than your debt and repossession costs—such as an auto loan with a $10,000 balance selling for $12,000—you are legally entitled to receive the leftover surplus funds once all repossession expenses are satisfied.
Repossession also carries long-term consequences for your credit history. The record of an auto repossession can remain on your credit files for up to seven years, raising future borrowing costs and potentially resulting in higher vehicle insurance premiums. If you believe your car was taken due to a servicer error, you can dispute the mark directly with the credit reporting bureaus, as noted in guidance on managing your credit reports.
Resolving Disputes and Unlawful Seizures
If you believe your car was repossessed improperly or by mistake, contact your loan servicer immediately to contest the action. If the company fails to correct the issue, the Consumer Financial Protection Bureau's guide on vehicle repossession advises submitting a formal complaint to the bureau, reaching out to your state attorney general, or consulting an attorney or a legal services office to protect your rights.
Sources
Consumer Financial Protection Bureau: What happens if my car is repossessed?
Published October 28, 2026. No affiliate links on this page. Facts come from the sources linked above; check them for updates.